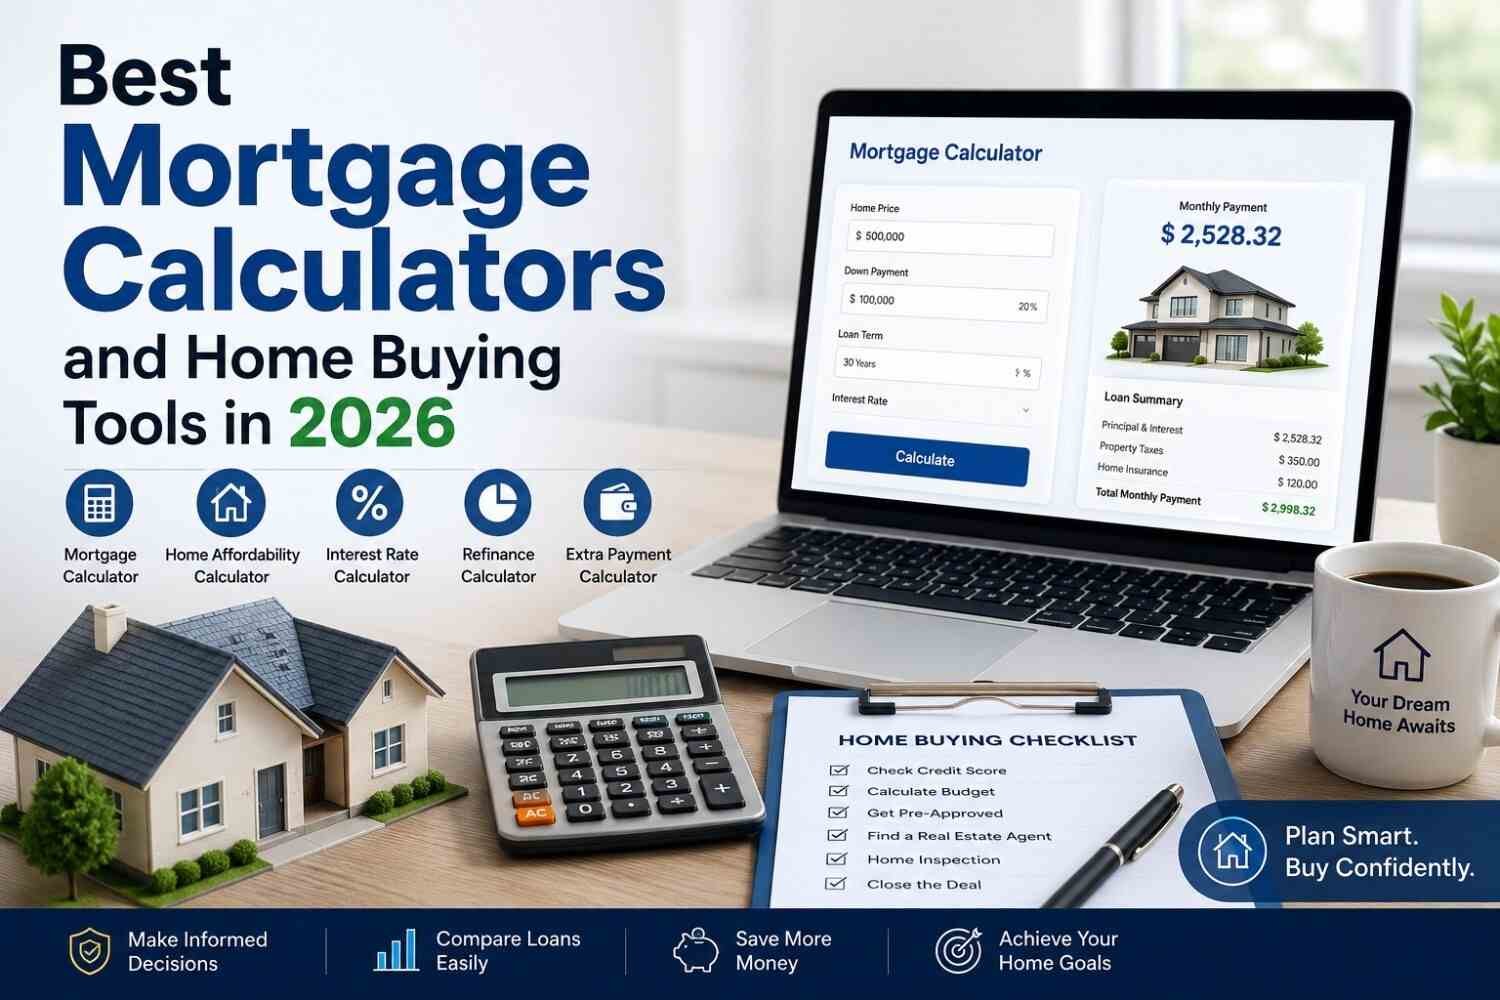
Buying a home is one of the biggest financial decisions most people make. Before choosing a property or applying for a mortgage loan, it is important to understand how much you can afford, what your monthly mortgage payment could be, and how interest rates can affect the total cost of your home.
Fortunately, modern mortgage calculators and home buying tools make it easier to estimate these numbers before you speak with a lender or start making offers.
Whether you are a first-time homebuyer or planning to refinance an existing mortgage, the right financial calculator can help you compare different scenarios and make better decisions.
What Is a Mortgage Calculator?
A mortgage calculator is a financial tool that estimates your monthly home loan payment based on factors such as:
- Home purchase price
- Down payment
- Mortgage interest rate
- Loan term
- Property taxes
- Homeowners insurance
- Private mortgage insurance
- Other housing costs
For example, if you are considering a $400,000 home, changing your down payment or interest rate can significantly change your estimated monthly payment. This makes a mortgage calculator useful before you decide how much house you can realistically afford.
Why Use a Mortgage Calculator Before Buying a Home?
Many buyers focus primarily on the purchase price of a property. However, the actual cost of homeownership can be considerably higher once financing and other expenses are included.
A mortgage calculator can help you estimate your:
Monthly Mortgage Payment
You can see approximately how much you may need to pay each month toward principal and interest.
Total Interest Cost
A longer mortgage term can result in lower monthly payments but potentially much higher total interest over the life of the loan.
Home Affordability
Instead of asking only, “How much does this house cost?” you can ask, “Can I comfortably afford the monthly payment?”
Down Payment Impact
Increasing your down payment can reduce the amount you need to borrow and may lower your monthly payment.
Interest Rate Impact
Even a relatively small change in the mortgage rate can affect your monthly payment and total borrowing costs.
The Most Useful Mortgage and Home Buying Tools
1. Mortgage Payment Calculator
A mortgage payment calculator is one of the most useful tools for prospective homebuyers. You typically enter home price, down payment, interest rate, and loan term. The calculator then estimates your monthly principal and interest payment.
Some advanced calculators also include property taxes, homeowners insurance and mortgage insurance to provide a more realistic estimate of your total monthly housing expense.
2. Home Affordability Calculator
A home affordability calculator works differently from a basic mortgage calculator. Instead of starting with a specific property price, it can help estimate what price range may fit your financial situation.
Factors may include annual income, monthly debt payments, down payment, credit profile, interest rate, and desired loan term. This can be particularly helpful for first-time homebuyers who are unsure about their realistic price range.
3. Mortgage Interest Calculator
Mortgage interest can represent a substantial portion of the total cost of borrowing. A mortgage interest calculator helps estimate how much interest you could pay over the life of a mortgage.
For example, two mortgages with similar monthly payments can have significantly different total interest costs depending on the interest rate and loan term. Understanding this difference can help you compare financing options more effectively.
4. Amortization Calculator
A mortgage amortization calculator shows how your mortgage balance changes over time. An amortization schedule can show monthly payment, principal paid, interest paid, remaining loan balance, and total interest paid.
This is useful when you want to understand how quickly you are building equity in your home.
5. Refinance Calculator
Homeowners with an existing mortgage can use a mortgage refinance calculator to estimate whether refinancing could potentially reduce their monthly payment or overall interest costs.
You can compare your current interest rate to a new interest rate, monthly payment to estimated new payment, and remaining balance to new loan amount. However, refinancing also involves costs and fees, so the potential savings should be considered alongside closing costs.
Mortgage Rates Can Have a Big Impact
One of the most important factors in determining your mortgage payment is the mortgage interest rate.
Consider two hypothetical buyers purchasing the same $400,000 property with the same down payment. If one buyer receives a lower interest rate, their monthly principal and interest payment could be lower. Over a long mortgage term, the difference in interest costs can become substantial.
That’s why it can be useful to compare different mortgage rate scenarios before applying for a home loan. A calculator lets you change the interest rate and immediately see how the estimated payment changes.
How Much House Can You Afford?
Knowing your maximum borrowing capacity isn’t necessarily the same as knowing what you should spend. A lender may evaluate factors such as income, existing debts, credit history, down payment, loan type, interest rate, and debt-to-income ratio.
A debt-to-income ratio calculator can help you understand how your existing monthly debt compares with your income. This can be an important part of evaluating your overall financial position before purchasing a home.
Down Payment Calculator
Your down payment can have a major impact on your mortgage. For example, increasing the down payment can reduce the amount borrowed, lower the monthly mortgage payment, reduce total interest costs, and potentially affect mortgage insurance requirements.
A down payment calculator allows buyers to compare different scenarios. Instead of asking whether you should put down a specific percentage, you can compare multiple options and see how each one changes your estimated monthly payment and borrowing costs.
Don’t Forget Property Taxes and Homeowners Insurance
Your mortgage payment isn’t always your complete housing expense. Homeowners may also need to budget for property taxes, homeowners insurance, mortgage insurance, homeowners association fees, maintenance, and utilities.
That’s why a simple principal-and-interest calculation may underestimate your actual monthly housing costs. An advanced home loan calculator that includes these expenses can provide a more realistic estimate.
Mortgage Calculator Example
Suppose you are considering a home priced at $500,000. You could compare scenarios such as:
| Scenario | Down Payment | Interest Rate | Loan Term |
|---|---|---|---|
| A | 10% | 6.5% | 30 years |
| B | 20% | 6.5% | 30 years |
| C | 20% | 6.0% | 30 years |
| D | 20% | 6.5% | 15 years |
Changing just one variable can significantly affect your estimated payment and total interest. This is why using a home loan calculator before shopping for a property can be valuable.
Mortgage Tools for First-Time Homebuyers
First-time buyers often have more questions because they may be unfamiliar with the home buying process. Useful tools include:
- Home Affordability Calculator – Helps estimate a reasonable purchase price based on financial information.
- Mortgage Payment Calculator – Estimates monthly principal and interest.
- Down Payment Calculator – Shows how different down payment amounts affect borrowing.
- Closing Cost Calculator – Helps estimate additional expenses associated with purchasing a home.
- Mortgage Amortization Calculator – Shows how payments are allocated between principal and interest.
- Debt-to-Income Calculator – Helps evaluate existing debt relative to income.
Using several tools together can provide a much clearer picture than relying on the purchase price alone.
How to Compare Mortgage Options
When comparing mortgage options, don’t focus exclusively on the monthly payment. Consider:
- Interest rate
- Loan term
- Annual percentage rate (APR)
- Closing costs
- Down payment requirements
- Mortgage insurance
- Total interest
- Potential fees
A mortgage with a slightly lower monthly payment isn’t necessarily the cheapest option over the entire loan period. The APR can be particularly useful when comparing loan offers because it can reflect certain costs beyond the basic interest rate.
Should You Use an Online Mortgage Calculator?
Yes. Online calculators are useful for estimates and comparisons before making financial decisions. They can help you create a realistic home buying budget, compare mortgage scenarios, understand interest costs, estimate monthly payments, evaluate different down payments, and compare loan terms.
However, calculator results are estimates. Actual mortgage terms depend on the lender, your financial circumstances, the property, prevailing rates and other factors.
Final Thoughts
Buying a home becomes much easier to evaluate when you understand the numbers behind the purchase.
A mortgage calculator, home affordability calculator, mortgage interest calculator, refinance calculator, amortization calculator and down payment calculator can help you compare different scenarios before you commit to a mortgage.
The most important goal isn’t simply finding the largest loan you can qualify for. It’s finding a home and financing structure that fits comfortably within your overall financial plan.
Before applying for a mortgage, compare multiple scenarios, review the total cost of borrowing, and speak with qualified financial or mortgage professionals when appropriate.